Mathematical Statistics

The Beta Distribution and Choosing a Continuous Model

Samir Orujov, PhD

ADA University, School of Business

Information Communication Technologies Agency, Statistics Unit

2026-09-27

🎬 The Idea in 2 Minutes

⬅ Previous lecture: 20 · The Gamma, Exponential and Chi-Square Distributions

Watch this short intuition video before (or after) the slides. Captions (English / Azərbaycanca): CC button. ▶ Watch on YouTube

🎯 Learning Objectives

By the end of this lecture, you will be able to:

  • Recognise a beta density \(f(y) \propto y^{\alpha-1}(1-y)^{\beta-1}\) on \([0, 1]\) and find its constant \(B(\alpha, \beta)\)

  • Read the shape of a beta density from \(\alpha\) and \(\beta\), and rescale it to any interval \([c, d]\)

  • Compute \(E(Y)\), \(V(Y)\) and beta probabilities by direct integration, by the binomial link, and with pbeta

  • Choose a continuous model for an economic quantity from theory, from its support, and from a histogram

🔁 Warm-up from last time

A server’s uptime between failures is exponential with mean 10 days. Using the memoryless property, what is \(P(Y > 15 \mid Y > 5)\)?

  • \(e^{-1} \approx 0.368\)
  • \(e^{-1.5} \approx 0.223\)
  • \(e^{-0.5} \approx 0.607\)
  • \(0.667\)

🗺️ Where We Are

Wackerly §§4.7–4.8

Saturday closed the gamma family: the exponential and the chi-square as special cases, all living on \((0, \infty)\). Waiting times and claim sizes, with no ceiling.

Many quantities in finance do have a ceiling. A recovery rate, a market share, a utilisation rate, a portfolio weight: each is a proportion, trapped between 0 and 1.

Today, the model built for that: the beta (§4.7). Then §4.8 steps back and asks how we pick among the Chapter 4 densities in the first place.

❓ Motivating Question

The workout desk’s problem

A Baku bank’s workout unit has closed 250 defaulted SME loans. The share of each exposure it recovered averaged 0.40, with a standard deviation of 0.20.

For loss-given-default provisioning it needs \(P(\text{recovery} < 0.20)\).

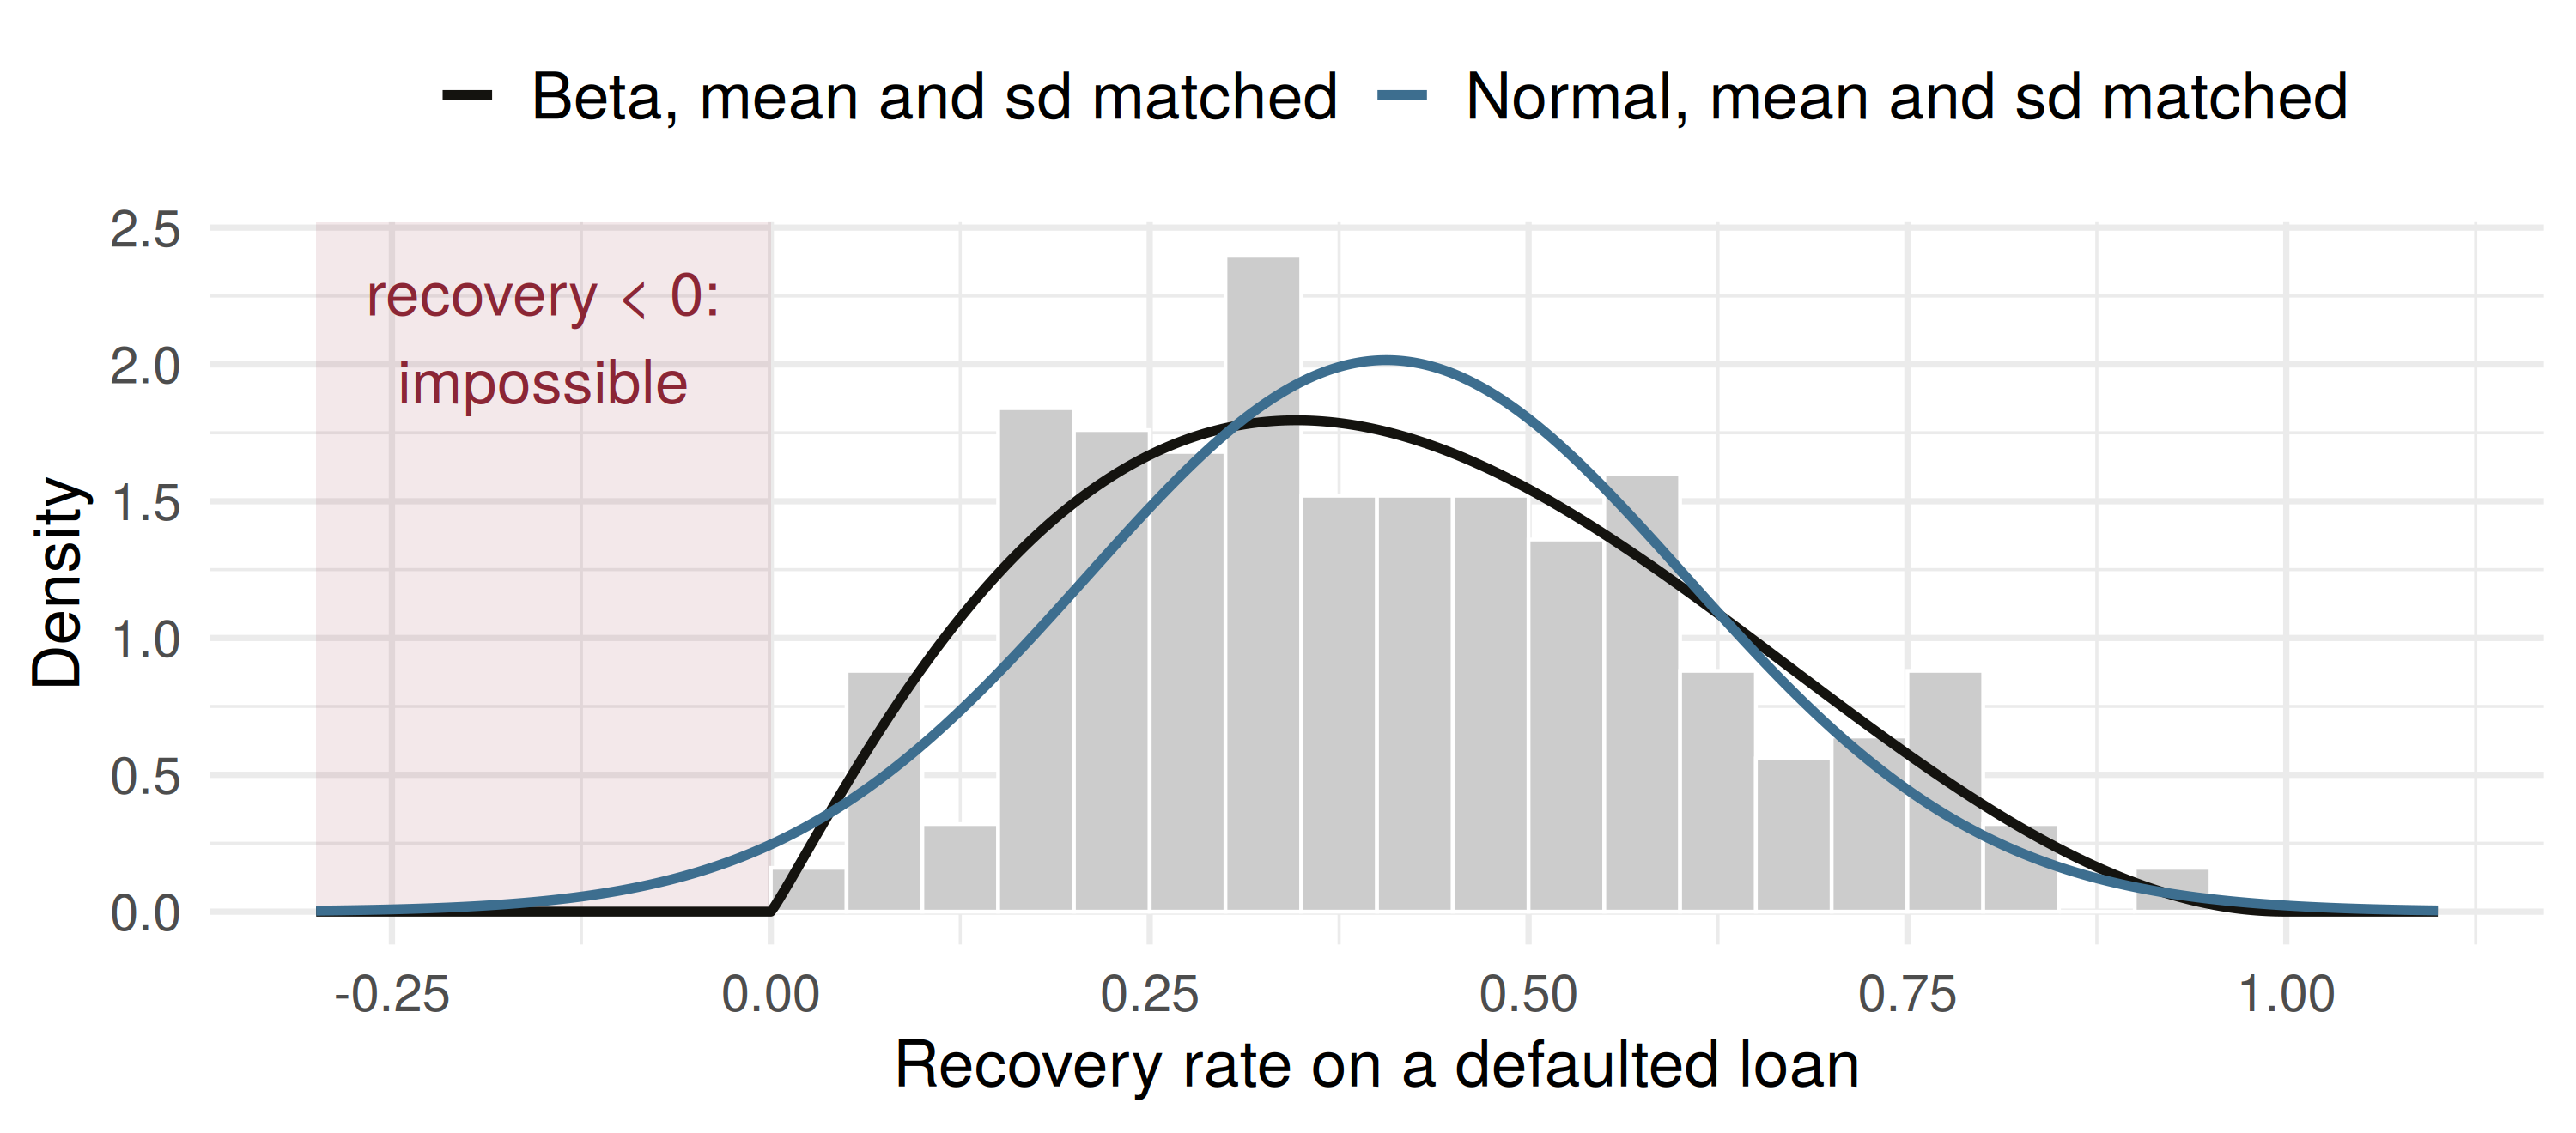
A normal with that mean and sd gives 0.159, and also puts 2.3% probability on recovering less than nothing. A model for a proportion must live on \([0, 1]\).

📐 Definition 4.12: The Beta Density

Definition 4.12

\(Y\) has a beta distribution with parameters \(\alpha > 0\) and \(\beta > 0\) if and only if its density is \[f(y) = \frac{y^{\alpha-1}(1-y)^{\beta-1}}{B(\alpha, \beta)}, \quad 0 \le y \le 1, \qquad f(y) = 0 \text{ elsewhere,}\] where \[B(\alpha, \beta) = \int_0^1 y^{\alpha-1}(1-y)^{\beta-1}\,dy = \frac{\Gamma(\alpha)\Gamma(\beta)}{\Gamma(\alpha+\beta)}\]

\(B(\alpha, \beta)\) only makes the area 1. With integers: \(B(2, 3) = 1!\,2!/4! = 1/12\), so \(f(y) = 12\,y(1-y)^2\).

🔬 Interactive: Two Parameters, Many Shapes

🧭 Reading the Shape

  • \(\alpha = \beta = 1\): \(f(y) = 1\), the uniform on \((0, 1)\) (Exercise 4.127)

  • \(\alpha = \beta\): symmetric about \(1/2\); larger values pull it tighter (Exercise 4.115)

  • \(\alpha < \beta\): mass nearer 0, skewed right; \(\alpha > \beta\): skewed left

  • \(\alpha, \beta > 1\): one hump, zero at both ends; setting \(f^{(1)}(y) = 0\) puts the mode at \(\dfrac{\alpha-1}{\alpha+\beta-2}\)

  • \(\alpha < 1\) or \(\beta < 1\): the density rises without bound at that edge

  • \(1 - Y\) is beta with the parameters swapped, \((\beta, \alpha)\) (a Chapter 6 result, Exercise 4.114)

📏 Beyond Proportions: Rescaling

If \(c \le y \le d\), then \(y^* = (y - c)/(d - c)\) lies in \([0, 1]\). The beta is not restricted to proportions; it is restricted to bounded quantities.

A pension fund’s mandate keeps its equity weight \(Y\) between 30% and 70%. Model \(Y^* = (Y - 0.30)/0.40\) as Beta(2, 2), so \(F(y) = 3y^2 - 2y^3\).

\[E(Y) = 0.30 + 0.40 \times 0.5 = 0.50\] \[P(Y > 0.60) = P(Y^* > 0.75) = 1 - F(0.75) = 1 - 0.84375 = 0.156\]

📐 Theorem 4.11: Mean and Variance

Theorem 4.11

If \(Y\) is beta with parameters \(\alpha > 0\) and \(\beta > 0\), \[\mu = E(Y) = \frac{\alpha}{\alpha + \beta} \qquad \text{and} \qquad \sigma^2 = V(Y) = \frac{\alpha\beta}{(\alpha+\beta)^2(\alpha+\beta+1)}\]

Proof of the mean. Multiplying by \(y\) adds one to the exponent, so the integral is another beta constant: \[E(Y) = \frac{B(\alpha+1, \beta)}{B(\alpha, \beta)} = \frac{\Gamma(\alpha+\beta)}{\Gamma(\alpha)\Gamma(\beta)} \cdot \frac{\alpha\,\Gamma(\alpha)\Gamma(\beta)}{(\alpha+\beta)\,\Gamma(\alpha+\beta)} = \frac{\alpha}{\alpha+\beta}\] The variance is Exercise 4.130.

🏦 Worked Example: Recovery Rates

The workout desk models the recovery rate as Beta(2, 3), so \(f(y) = 12\,y(1-y)^2\) on \([0, 1]\).

\[E(Y) = \frac{2}{5} = 0.40, \qquad V(Y) = \frac{2 \times 3}{5^2 \times 6} = 0.04, \qquad \sigma = 0.20\] It matches the desk’s mean and standard deviation.

\[P(Y < 0.2) = \int_0^{0.2} 12\,(y - 2y^2 + y^3)\,dy = \Big[\,6y^2 - 8y^3 + 3y^4\,\Big]_0^{0.2}\] \[= 0.24 - 0.064 + 0.0048 = 0.1808\] The normal said 0.159. About 18% of defaulted loans recover under a fifth, and the beta never predicts a negative recovery.

💻 The Same Numbers in R

pbeta(0.2, shape1 = 2, shape2 = 3)          # P(Y < 0.2)
[1] 0.1808
1 - pbinom(1, size = 4, prob = 0.2)         # binomial link: P(W >= 2)
[1] 0.1808
qbeta(c(0.50, 0.95), 2, 3)                  # median and 95th percentile
[1] 0.3857276 0.7513954
rec <- rbeta(1e5, 2, 3)                     # 100,000 simulated recoveries
round(c(mean = mean(rec), sd = sd(rec), below_0.2 = mean(rec < 0.2)), 4)
     mean        sd below_0.2 
   0.4004    0.2004    0.1803 

The book prints pbeta(y0, α, 1/β), a reciprocal carried over from the gamma; for the beta the call is pbeta(y0, α, β).

⛽ Worked Example: A Pipeline

Example 4.11, moved to an export pipeline. The fraction \(Y\) of weekly capacity actually shipped is Beta(4, 2). Above 90% the operator pays a congestion surcharge. How often?

\[f(y) = \frac{\Gamma(6)}{\Gamma(4)\Gamma(2)}\,y^3(1-y) = 20\,(y^3 - y^4), \qquad 0 \le y \le 1\]

\[P(Y > 0.9) = 20\left[\frac{y^4}{4} - \frac{y^5}{5}\right]_{0.9}^{1} = 20 \times 0.004073 = 0.0815\] Roughly one week in twelve; the book rounds it to 0.08. The mean utilisation is \(4/6 = 0.667\), with \(\sigma = 0.178\).

🧠 Think-Pair-Share

A mobile operator’s share \(Y\) of new subscriptions in a region, month by month, is modelled as Beta(7, 13).

Four minutes, in pairs:

  1. Find \(E(Y)\) and the standard deviation of \(Y\).

  2. What is the most likely share (the mode)?

  3. The rivals together hold \(1 - Y\). What is its distribution, and its mean?

✅ Think-Pair-Share: Solution

  1. Theorem 4.11 with \(\alpha + \beta = 20\): \[E(Y) = \frac{7}{20} = 0.35, \qquad V(Y) = \frac{7 \times 13}{20^2 \times 21} = 0.01083, \qquad \sigma = 0.104\]

  2. Both parameters exceed 1, so the mode is \(\dfrac{7 - 1}{20 - 2} = \dfrac{1}{3}\), just below the mean: the density is skewed right.

  1. Swap the parameters: \(1 - Y\) is Beta(13, 7), with mean \(13/20 = 0.65 = 1 - 0.35\) and the same standard deviation, since the formula for \(V\) is symmetric in \(\alpha, \beta\).

🧭 §4.8: How Do We Choose a Model?

No density is a perfect picture of nature. A good model is one that yields good inferences about the population, not one that fits every bump.

Wackerly names three routes:

  1. Theory. Poisson events in time make the gap between them exponential, and the time from the \(a\)th to the \(b\)th event gamma with \(\alpha = b - a\). The central limit theorem (Chapter 7) points to the normal.

  2. A histogram (Chapter 1) of sample data, compared with candidate curves.

  3. Formal tests of fit, later in the course.

🗂️ Start From the Support

Model Support Typical economic quantity
Uniform\((\theta_1, \theta_2)\) \([\theta_1, \theta_2]\) arrival time inside a settlement window
Normal\((\mu, \sigma^2)\) \((-\infty, \infty)\) a daily return, a forecast error
Exponential, gamma, \(\chi^2\) \((0, \infty)\) time between events, a claim amount
Beta\((\alpha, \beta)\) \([0, 1]\), or \([c, d]\) rescaled recovery rate, market share, utilisation, a weight

The support rules models out before any data are seen. Within what is left, the shape of a histogram decides.

💻 Fitting the Recoveries

set.seed(2026)
recov <- rbeta(250, 2, 3)          # stand-in for the desk's 250 closed files
m <- mean(recov); s <- sd(recov)
k <- m * (1 - m) / s^2 - 1         # Theorem 4.11 solved for alpha + beta
round(c(mean = m, sd = s, alpha = m * k, beta = (1 - m) * k), 3)
 mean    sd alpha  beta 
0.406 0.198 2.095 3.063 
round(c(normal_below_0 = pnorm(0, m, s),
        beta_below_0.2 = pbeta(0.2, m * k, (1 - m) * k),
        data_below_0.2 = mean(recov < 0.2)), 3)
normal_below_0 beta_below_0.2 data_below_0.2 
         0.020          0.168          0.160 

Matching the sample mean and sd recovers \(\alpha \approx 2.1\), \(\beta \approx 3.1\). The normal still spends 2% on impossible values.

📈 Two Candidates, One Histogram

💰 Case Study: Fitting Capacity Utilisation With a Beta

📈 The question

Industrial capacity utilisation is a proportion, \(Y \in [0, 1]\).

  1. Matching the sample mean and sd to Theorem 4.11, what \(\alpha\) and \(\beta\) result?
  2. Does that beta predict \(P(Y < 0.75)\) and \(P(Y > 0.80)\) well?
  3. Where does treating each month as an independent beta draw break down?

📊 The data

Series: Total industry capacity utilisation (FRED TCU)

Period: Sep 2016 – Aug 2026, 120 months

Variable: \(Y\) = TCU / 100

💰 Case Study: Matching Moments in R

📦 Load the data and match alpha, beta to the mean and sd
tcu <- read.csv("data/tcu.csv", col.names = c("date", "tcu"))
tcu$tcu <- suppressWarnings(as.numeric(tcu$tcu))   # FRED marks holidays "."
tcu <- na.omit(tcu)

y <- tcu$tcu / 100
m <- mean(y); s <- sd(y)
k <- m * (1 - m) / s^2 - 1                          # Theorem 4.11 solved for alpha + beta
a_hat <- m * k; b_hat <- (1 - m) * k

round(c(mean_Y = m, sd_Y = s, alpha = a_hat, beta = b_hat,
        P_below_0.75_beta = pbeta(0.75, a_hat, b_hat),
        P_below_0.75_data = mean(y < 0.75),
        P_above_0.80_beta = pbeta(0.80, a_hat, b_hat, lower.tail = FALSE),
        P_above_0.80_data = mean(y > 0.80)), 4)
           mean_Y              sd_Y             alpha              beta 
           0.7663            0.0229          259.9650           79.2605 
P_below_0.75_beta P_below_0.75_data P_above_0.80_beta P_above_0.80_data 
           0.2349            0.1000            0.0674            0.0000 

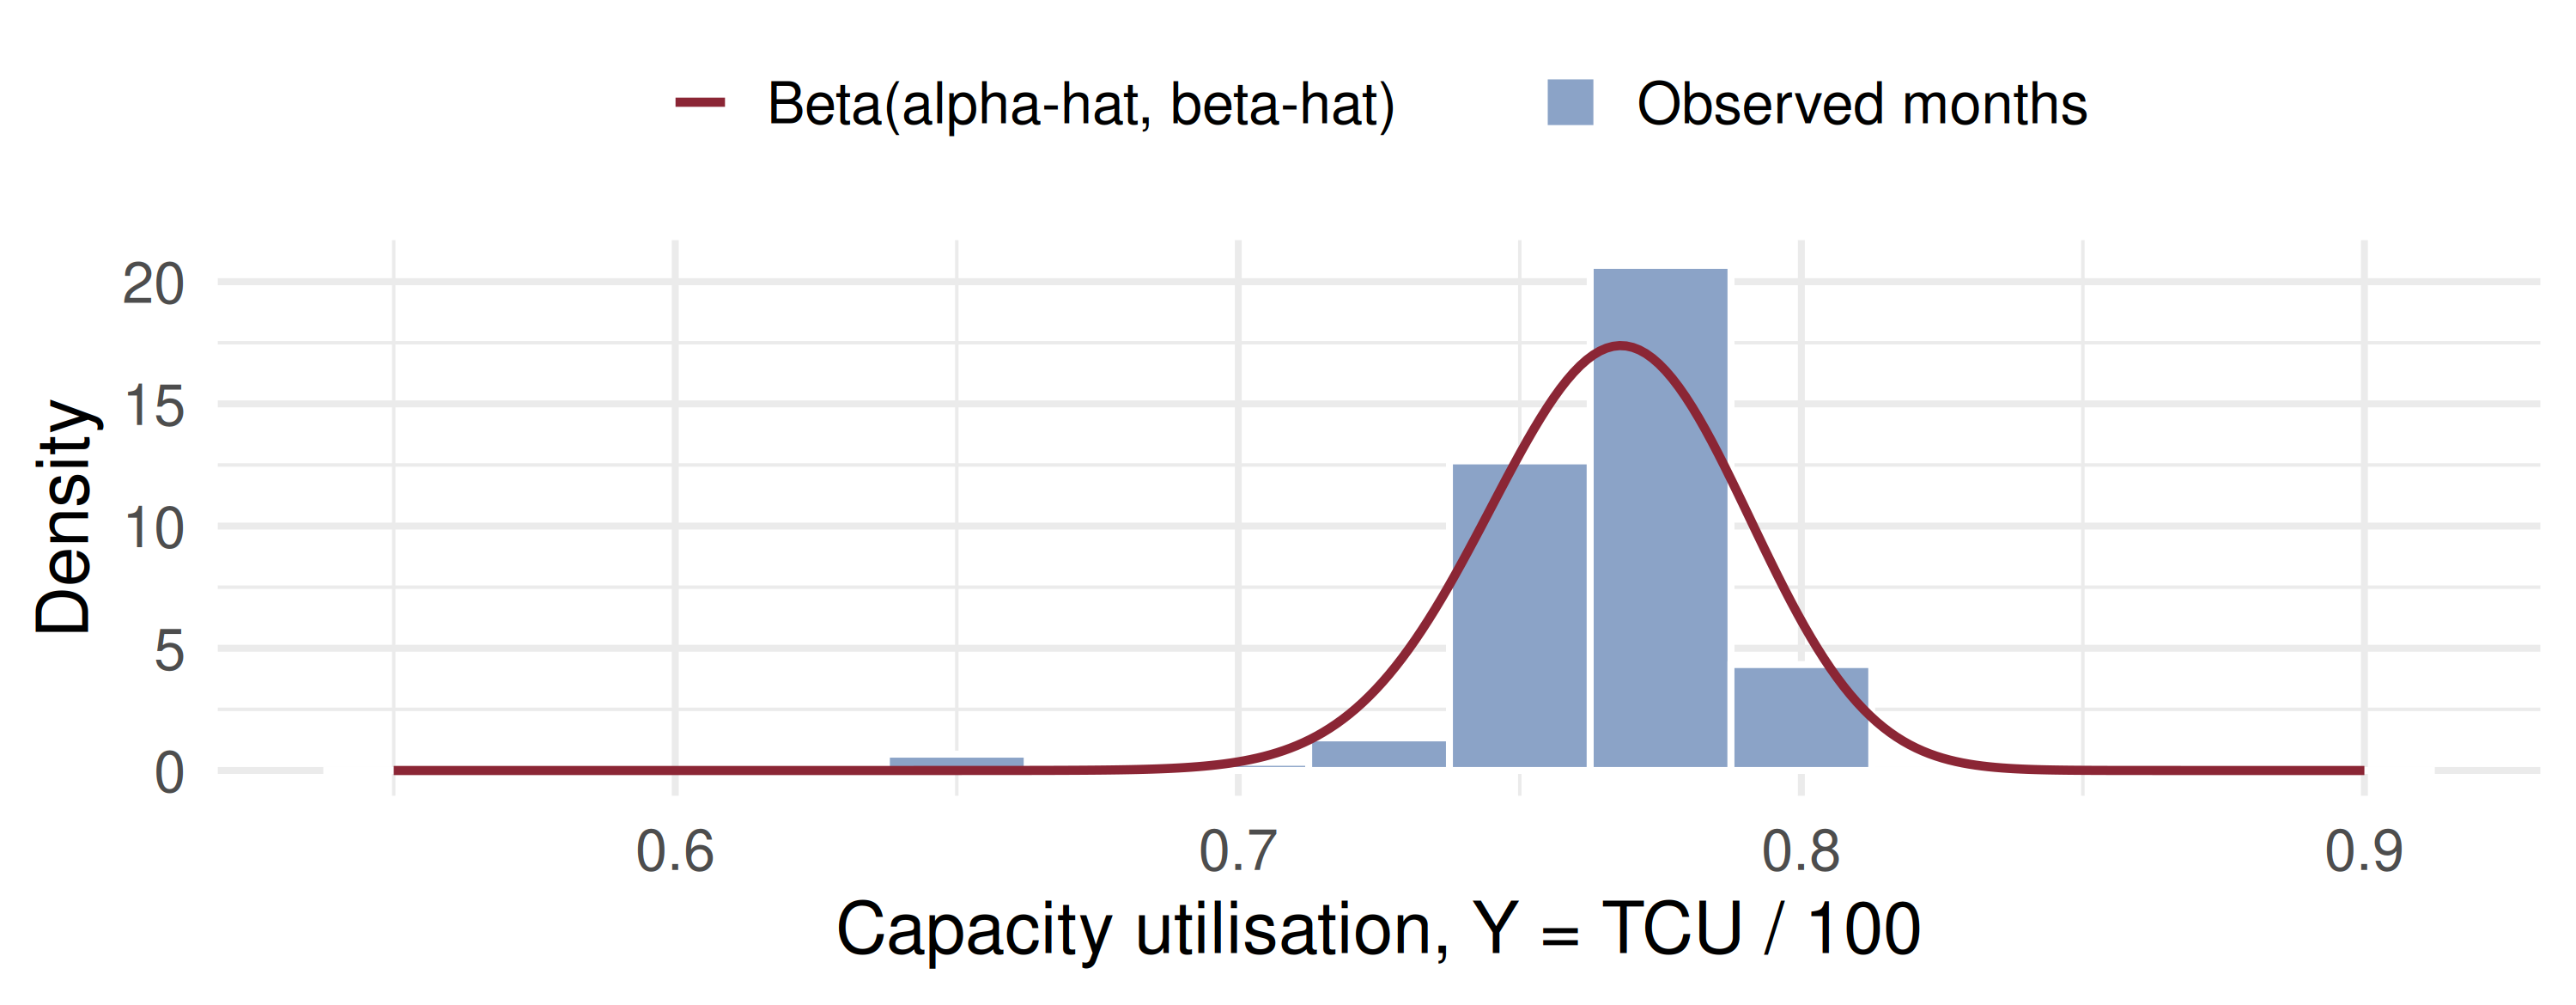
The moment-matched beta puts real weight below 0.75 and above 0.80; the data almost never go there.

💰 Case Study: A Peaked Series, a Wider Beta

What the data say: the beta curve centres correctly and is roughly the right width. It fails because utilisation moves slowly from month to month rather than resetting independently, so the true series stays inside a narrower band (0.64 to 0.80) than 120 independent beta draws would produce.

📝 Quiz #1: The Mean

A telecom regulator models an operator’s market share as Beta(3, 7). What is its expected share?

  • \(0.30\)
  • \(0.43\)
  • \(0.70\)
  • \(0.019\)

📝 Quiz #2: The Shape

Recovery rates on unsecured consumer loans follow Beta(2, 8). Which description fits?

  • Skewed right: most recoveries are small, with a tail towards 1
  • Symmetric about 0.5
  • Skewed left: most recoveries are close to 1
  • Uniform on [0, 1]

📝 Quiz #3: Choosing a Model

A fund reports the proportion of its assets held in equities each quarter. Which model respects what that number can be?

  • Beta, because the proportion lies in [0, 1]
  • Normal, because averages tend to be normal
  • Exponential, because it is positive
  • Poisson, because it is reported at regular intervals

📋 Key Formulas

Statement
Definition 4.12 \(f(y) = \dfrac{y^{\alpha-1}(1-y)^{\beta-1}}{B(\alpha, \beta)}\), \(\; 0 \le y \le 1\)
beta function \(B(\alpha, \beta) = \dfrac{\Gamma(\alpha)\Gamma(\beta)}{\Gamma(\alpha+\beta)}\)
Theorem 4.11, mean \(E(Y) = \alpha/(\alpha+\beta)\)
Theorem 4.11, variance \(V(Y) = \dfrac{\alpha\beta}{(\alpha+\beta)^2(\alpha+\beta+1)}\)
binomial link, \(n = \alpha+\beta-1\) \(F(y) = \sum_{i=\alpha}^{n} \binom{n}{i} y^i(1-y)^{n-i}\)
in R pbeta(y0, α, β), qbeta(p, α, β)

📋 Summary

  • The beta is the Chapter 4 model for a bounded quantity: a proportion, or anything rescaled to \([0, 1]\)

  • \(\alpha\) and \(\beta\) set the shape: symmetric, skewed either way, humped or U-shaped; \((1, 1)\) is the uniform

  • \(E(Y) = \alpha/(\alpha + \beta)\); with integer parameters the CDF is a binomial tail

  • A good model yields good inferences; perfect fit is not the test

  • Choose by theory, then by support, then by the histogram

📚 Practice Problems

Wackerly, 7th edition

  • §4.7: Exercises 4.124 – 4.134; start with 4.124, 4.125, 4.128, 4.132 and 4.134(a)

  • Applet Exercises 4.114 – 4.119: use today’s slider in place of the applet

  • Redo the workout desk with Beta(3, 4.5): same mean, smaller spread. What happens to \(P(Y < 0.2)\)?

Week 11, Problem Set 1 is open now and closes Sunday 29 November at 23:59 on WeBWorK, covering §§4.7–4.8.

Next class: 21 November, other expected values, Tchebysheff’s theorem for continuous variables, and Chapter 4 in review (Wackerly §§4.9–4.11).

🙏 Thank You

Dr. Samir Orujov

📧 sorujov@ada.edu.az
🏢 Building D, Room D325
🕓 Office hours: Wednesday, 16:00 – 18:00

Slides and readings: sorujov.net/teaching

❓ Questions

  • Beta(2, 3) and Beta(20, 30) have the same mean. How do their standard deviations compare, and what does that say about the evidence behind each?

  • Why does the beta density blow up at 0 when \(\alpha < 1\), and could a recovery-rate distribution plausibly look like that?

  • A loss rate can be exactly 0 for many loans. Can a continuous beta model that point mass?