Mathematical Statistics

Bivariate and Multivariate Probability Distributions

Samir Orujov, PhD

ADA University, School of Business

Information Communication Technologies Agency, Statistics Unit

2026-09-27

🎬 The Idea in 3 Minutes

⬅ Previous lecture: 22 · Other Expected Values, Tchebysheff’s Theorem, and Chapter 4 in Review

Watch this short intuition video before (or after) the slides. Captions (English / Azərbaycanca): CC button. ▶ Watch on YouTube

🎯 Learning Objectives

By the end of this lecture, you will be able to:

  • Explain why two marginal probabilities do not determine the probability of a joint event

  • Construct a joint probability function from a sample space, and check it against Theorem 5.1

  • Evaluate a joint distribution function \(F(y_1, y_2)\) from a table, including the rectangle rule of Theorem 5.2

  • Compute a joint probability as a double integral of a joint density over a sketched region

  • Extend the definitions from two random variables to \(n\)

🔁 Warm-up from last time

By Theorem 4.13 (Tchebysheff), what upper bound does the theorem give for \(P(|Y-\mu| \ge 5\sigma)\), for any distribution with finite mean and variance?

  • \(1/25 = 0.04\)
  • \(1/5 = 0.2\)
  • \(0.0027\) (the normal’s exact value)
  • It cannot be bounded without knowing the distribution

🗺️ Where We Are

Wackerly §5.1–5.2 — the start of Chapter 5

Saturday closed Chapter 4: one continuous random variable at a time — its density, its expected values, its MGF, and Tchebysheff’s bound on how far it strays.

Every model so far has described one quantity. A loan book, a portfolio, a payment system is never one quantity.

Today the object becomes a pair \((Y_1, Y_2)\), and the question becomes how two random variables behave together. This chapter carries the rest of the course.

❓ The Question This Lecture Answers

Two SME borrowers of a Baku bank, both in construction, each default within the year with probability \(0.07\). What is the probability that both default?

  • If they are unrelated: \(0.07 \times 0.07 = 0.0049\)
  • If they always move together: \(0.07\)

A fourteen-fold range, and the two marginals cannot choose between them. The answer lives in the joint distribution, which §5.2 defines.

§5.1: every sample \((y_1, \ldots, y_n)\) is also such an intersection, \((Y_1 = y_1, \ldots, Y_n = y_n)\). We build the tools with \(n = 2\), then extend.

📐 Definition 5.1 and Theorem 5.1

Definition 5.1

Let \(Y_1\) and \(Y_2\) be discrete random variables. The joint (or bivariate) probability function for \(Y_1\) and \(Y_2\) is \[p(y_1, y_2) = P(Y_1 = y_1, Y_2 = y_2), \quad -\infty < y_1 < \infty,\ -\infty < y_2 < \infty.\]

Theorem 5.1

  1. \(p(y_1, y_2) \ge 0\) for all \(y_1, y_2\).
  2. \(\sum_{y_1, y_2} p(y_1, y_2) = 1\), summing over all pairs given nonzero probability.

🏦 Routing Two Loan Applications

Two applications are each sent at random, independently, to committee 1 (Corporate), 2 (SME) or 3 (Retail). \(Y_1\) = number sent to Corporate, \(Y_2\) = number to SME. All \(3 \times 3 = 9\) routings \(\{i, j\}\) are equally likely.

\(y_1 = 0\) \(y_1 = 1\) \(y_1 = 2\)
\(y_2 = 0\) \(1/9\) \(2/9\) \(1/9\)
\(y_2 = 1\) \(2/9\) \(2/9\) \(0\)
\(y_2 = 2\) \(1/9\) \(0\) \(0\)

\(p(1,1) = 2/9\): both \(\{1,2\}\) and \(\{2,1\}\) give it. The zeros say \(Y_1 + Y_2 \le 2\): the support is a region, not a rectangle.

📈 Joint Returns of Two Assets

Monthly returns (%) on a Baku-listed bank share, \(Y_1\), and an oil-sector bond fund, \(Y_2\):

\(y_2 = -1\) \(y_2 = 1\) \(y_2 = 3\)
\(y_1 = -2\) \(0.10\) \(0.08\) \(0.02\)
\(y_1 = 0\) \(0.06\) \(0.30\) \(0.09\)
\(y_1 = 4\) \(0.02\) \(0.12\) \(0.21\)
  • Both gain: \(p(4,1) + p(4,3) = 0.33\). Both lose: \(p(-2,-1) = 0.10\).
  • An equal-weight portfolio gains when \(y_1 + y_2 > 0\): six cells, total \(0.76\).

💻 The Table in R

Code
p <- matrix(c(0.10, 0.08, 0.02,
              0.06, 0.30, 0.09,
              0.02, 0.12, 0.21), nrow = 3, byrow = TRUE,
            dimnames = list(y1 = c(-2, 0, 4), y2 = c(-1, 1, 3)))
y1 <- as.numeric(rownames(p)); y2 <- as.numeric(colnames(p))
Fjoint <- function(a, b) sum(p[y1 <= a, y2 <= b])     # Definition 5.2
c(min = min(p), total = sum(p),                        # Theorem 5.1
  both_gain = sum(p[y1 > 0, y2 > 0]),
  port_gain = sum(p[outer(y1, y2, "+") > 0]),
  F01 = Fjoint(0, 1), F4m1 = Fjoint(4, -1))
      min     total both_gain port_gain       F01      F4m1 
     0.02      1.00      0.33      0.76      0.54      0.18 
🖼️ Mass Sits on the Diagonal

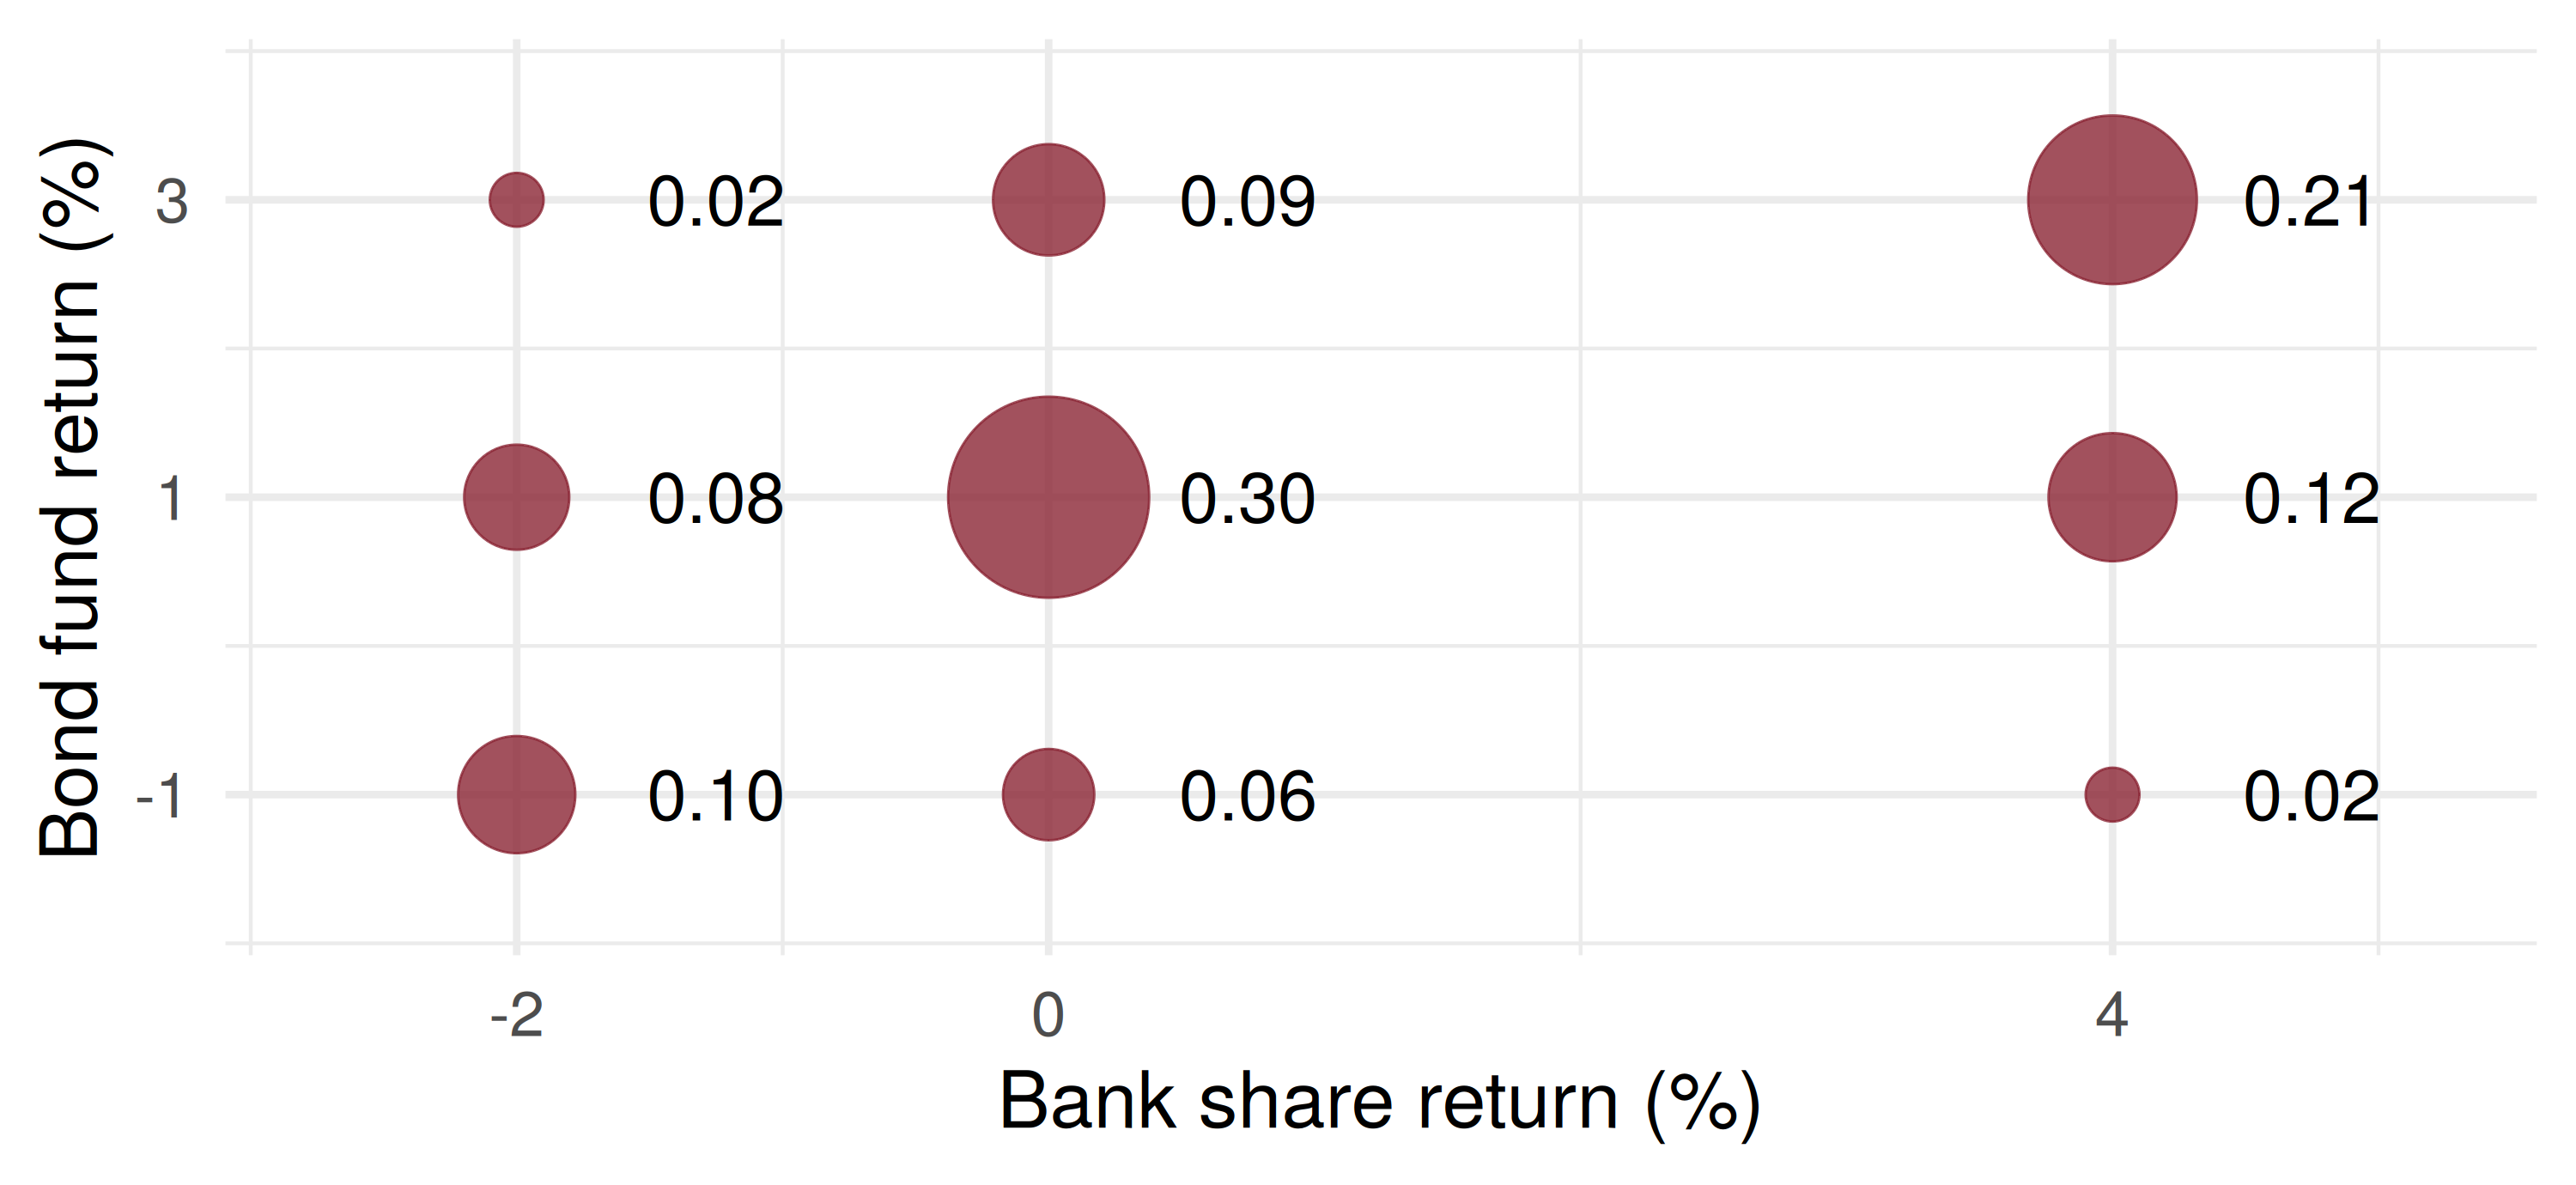
The large masses run from bottom left to top right: the two assets tend to move together.

📐 Definition 5.2: The Joint CDF

Definition 5.2

For any random variables \(Y_1\) and \(Y_2\), the joint distribution function is \(F(y_1, y_2) = P(Y_1 \le y_1, Y_2 \le y_2)\). For discrete variables, \(F(y_1, y_2) = \sum_{t_1 \le y_1} \sum_{t_2 \le y_2} p(t_1, t_2)\).

On the returns table:

  • \(F(0, 1) = 0.10 + 0.08 + 0.06 + 0.30 = 0.54\)
  • \(F(0.5, 1.5) = 0.54\) as well — no new mass between the grid points
  • \(F(-3, 5) = 0\) and \(F(5, 5) = 1\)

📐 Theorem 5.2: Properties of \(F\)

Theorem 5.2

  1. \(F(-\infty, -\infty) = F(-\infty, y_2) = F(y_1, -\infty) = 0\).
  2. \(F(\infty, \infty) = 1\).
  3. If \(y_1^* \ge y_1\) and \(y_2^* \ge y_2\), then \(F(y_1^*, y_2^*) - F(y_1^*, y_2) - F(y_1, y_2^*) + F(y_1, y_2) \ge 0\).

Part 3 is \(P(y_1 < Y_1 \le y_1^*,\ y_2 < Y_2 \le y_2^*)\): the rectangle rule. On the returns table, \[P(-2 < Y_1 \le 4,\ -1 < Y_2 \le 3) = 1 - 0.18 - 0.20 + 0.10 = 0.72,\] which is the four cells \(0.30 + 0.09 + 0.12 + 0.21\).

💰 Case Study: The Joint Table of Two Real Assets

📈 The question

Classify each day as \(Y_1\) = S&P 500 up/down and \(Y_2\) = Brent crude up/down.

  1. Built from data, does the \(2\times 2\) table satisfy Theorem 5.1?
  2. Is mass spread evenly across the four cells?
  3. Do the two assets move together more often than separately?

📊 The data

Series: S&P 500 close (SP500), Brent crude (DCOILBRENTEU)

Period: Sep 2016 – Sep 2026, about 2,470 matched days

Variables: \(Y_1, Y_2 \in \{\text{down}, \text{up}\}\), daily log return sign

💰 Case Study: Building the Table in R

📦 Load both series and build the joint table
sp <- read.csv("data/sp500.csv", col.names = c("date", "close"))
sp$close <- suppressWarnings(as.numeric(sp$close))   # FRED marks holidays "."
sp <- na.omit(sp)
br <- read.csv("data/brent.csv", col.names = c("date", "close"))
br$close <- suppressWarnings(as.numeric(br$close))
br <- na.omit(br)

sp_r <- data.frame(date = sp$date[-1], r1 = diff(log(sp$close)))
br_r <- data.frame(date = br$date[-1], r2 = diff(log(br$close)))
m <- merge(sp_r, br_r, by = "date")                  # keep only common trading days

y1 <- ifelse(m$r1 > 0, "up", "down"); y2 <- ifelse(m$r2 > 0, "up", "down")
joint <- prop.table(table(SP500 = y1, Brent = y2))

data.frame(
  cell  = c("SP500 down, Brent down", "SP500 down, Brent up",
            "SP500 up, Brent down",   "SP500 up, Brent up",
            "total", "corr(r1, r2)"),
  value = round(c(as.vector(t(joint)), sum(joint), cor(m$r1, m$r2)), 3)
)
                    cell value
1 SP500 down, Brent down 0.228
2   SP500 down, Brent up 0.223
3   SP500 up, Brent down 0.247
4     SP500 up, Brent up 0.301
5                  total 1.000
6           corr(r1, r2) 0.185

The table sums to 1, as Theorem 5.1 requires, and the diagonal cells (both up, both down) carry the most mass.

💰 Case Study: The Returns, Day by Day

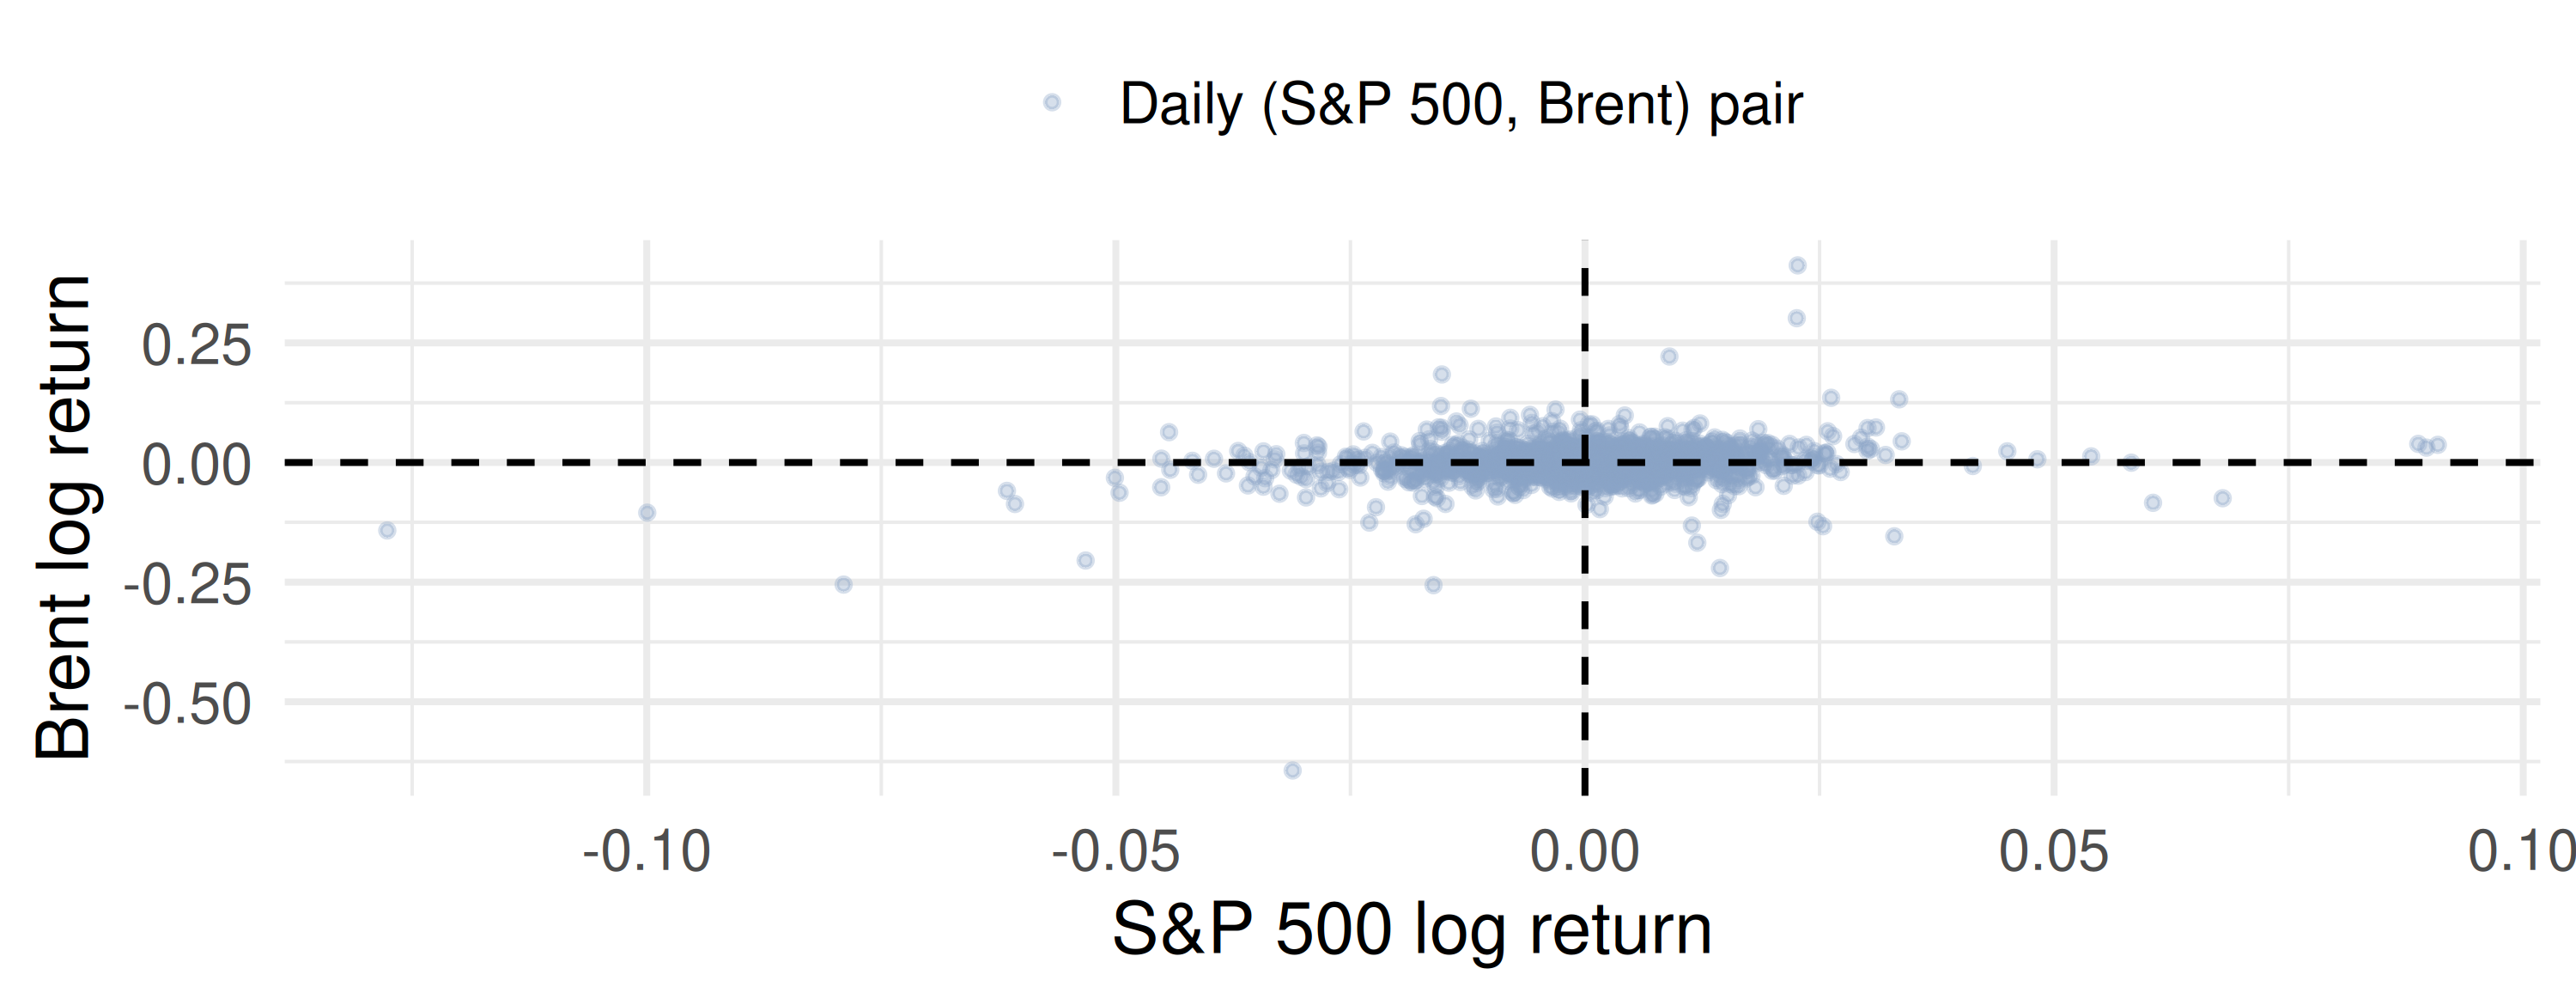
What the data say: points sit somewhat more in the bottom-left and top-right quadrants, matching the table’s diagonal weight and a small positive correlation (\(r \approx 0.19\)). The fit is loose, not tight: many days still land in the mixed quadrants, so knowing \(Y_1\)’s sign narrows \(Y_2\)’s odds a little, not decides them.

📝 Quiz #1: Reading \(F\) From a Table

In the joint returns table, what is \(F(4, -1) = P(Y_1 \le 4, Y_2 \le -1)\)?

  • \(0.18\)
  • \(0.02\)
  • \(0.10\)
  • \(1\)

📐 Definition 5.3 and Theorem 5.3

Definition 5.3

If there is a nonnegative \(f(y_1, y_2)\) with \(F(y_1, y_2) = \int_{-\infty}^{y_1} \int_{-\infty}^{y_2} f(t_1, t_2)\, dt_2\, dt_1\) for all \(y_1, y_2\), then \(Y_1, Y_2\) are jointly continuous, and \(f\) is the joint probability density function.

Theorem 5.3

  1. \(f(y_1, y_2) \ge 0\) for all \(y_1, y_2\).
  2. \(\int_{-\infty}^{\infty} \int_{-\infty}^{\infty} f(y_1, y_2)\, dy_1\, dy_2 = 1\).

Probabilities are now volumes: \(P(a_1 \le Y_1 \le a_2,\ b_1 \le Y_2 \le b_2) = \int_{b_1}^{b_2} \int_{a_1}^{a_2} f(y_1, y_2)\, dy_1\, dy_2\).

⏱️ Two Settlement Times

An AZN/USD foreign-exchange trade settles in two legs. \(Y_1\) = hours until the first leg settles, \(Y_2\) = hours until the second. By construction \(Y_1 \le Y_2\). Suppose \[f(y_1, y_2) = \begin{cases} 2e^{-(y_1 + y_2)}, & 0 \le y_1 \le y_2 < \infty,\\ 0, & \text{elsewhere.} \end{cases}\]

Check Theorem 5.3. \(f \ge 0\), and, integrating \(y_1\) first over \(0 \le y_1 \le y_2\), \[\int_0^\infty 2e^{-y_2}\left(1 - e^{-y_2}\right) dy_2 = 2\left(1 - \tfrac{1}{2}\right) = 1.\]

✏️ Worked Example: Two Probabilities

Both legs settled within one hour. Only \(Y_2 \le 1\) bites, because \(Y_1 \le Y_2\): \[F(1, 1) = \int_0^1 \int_0^{y_2} 2e^{-(y_1 + y_2)}\, dy_1\, dy_2 = 2(1 - e^{-1}) - (1 - e^{-2}) = (1 - e^{-1})^2 = 0.3996\]

First leg within 30 minutes, second after an hour. The rectangle \(0 \le y_1 \le 0.5,\ y_2 > 1\) lies wholly inside the support: \[\int_0^{0.5} \int_1^{\infty} 2e^{-(y_1 + y_2)}\, dy_2\, dy_1 = 2e^{-1}\left(1 - e^{-0.5}\right) = 0.2895\]

⚠️ Settlement Risk: The Gap

While one leg has settled and the other has not, the bank is exposed to its counterparty. What is \(P(Y_2 - Y_1 > 1)\)?

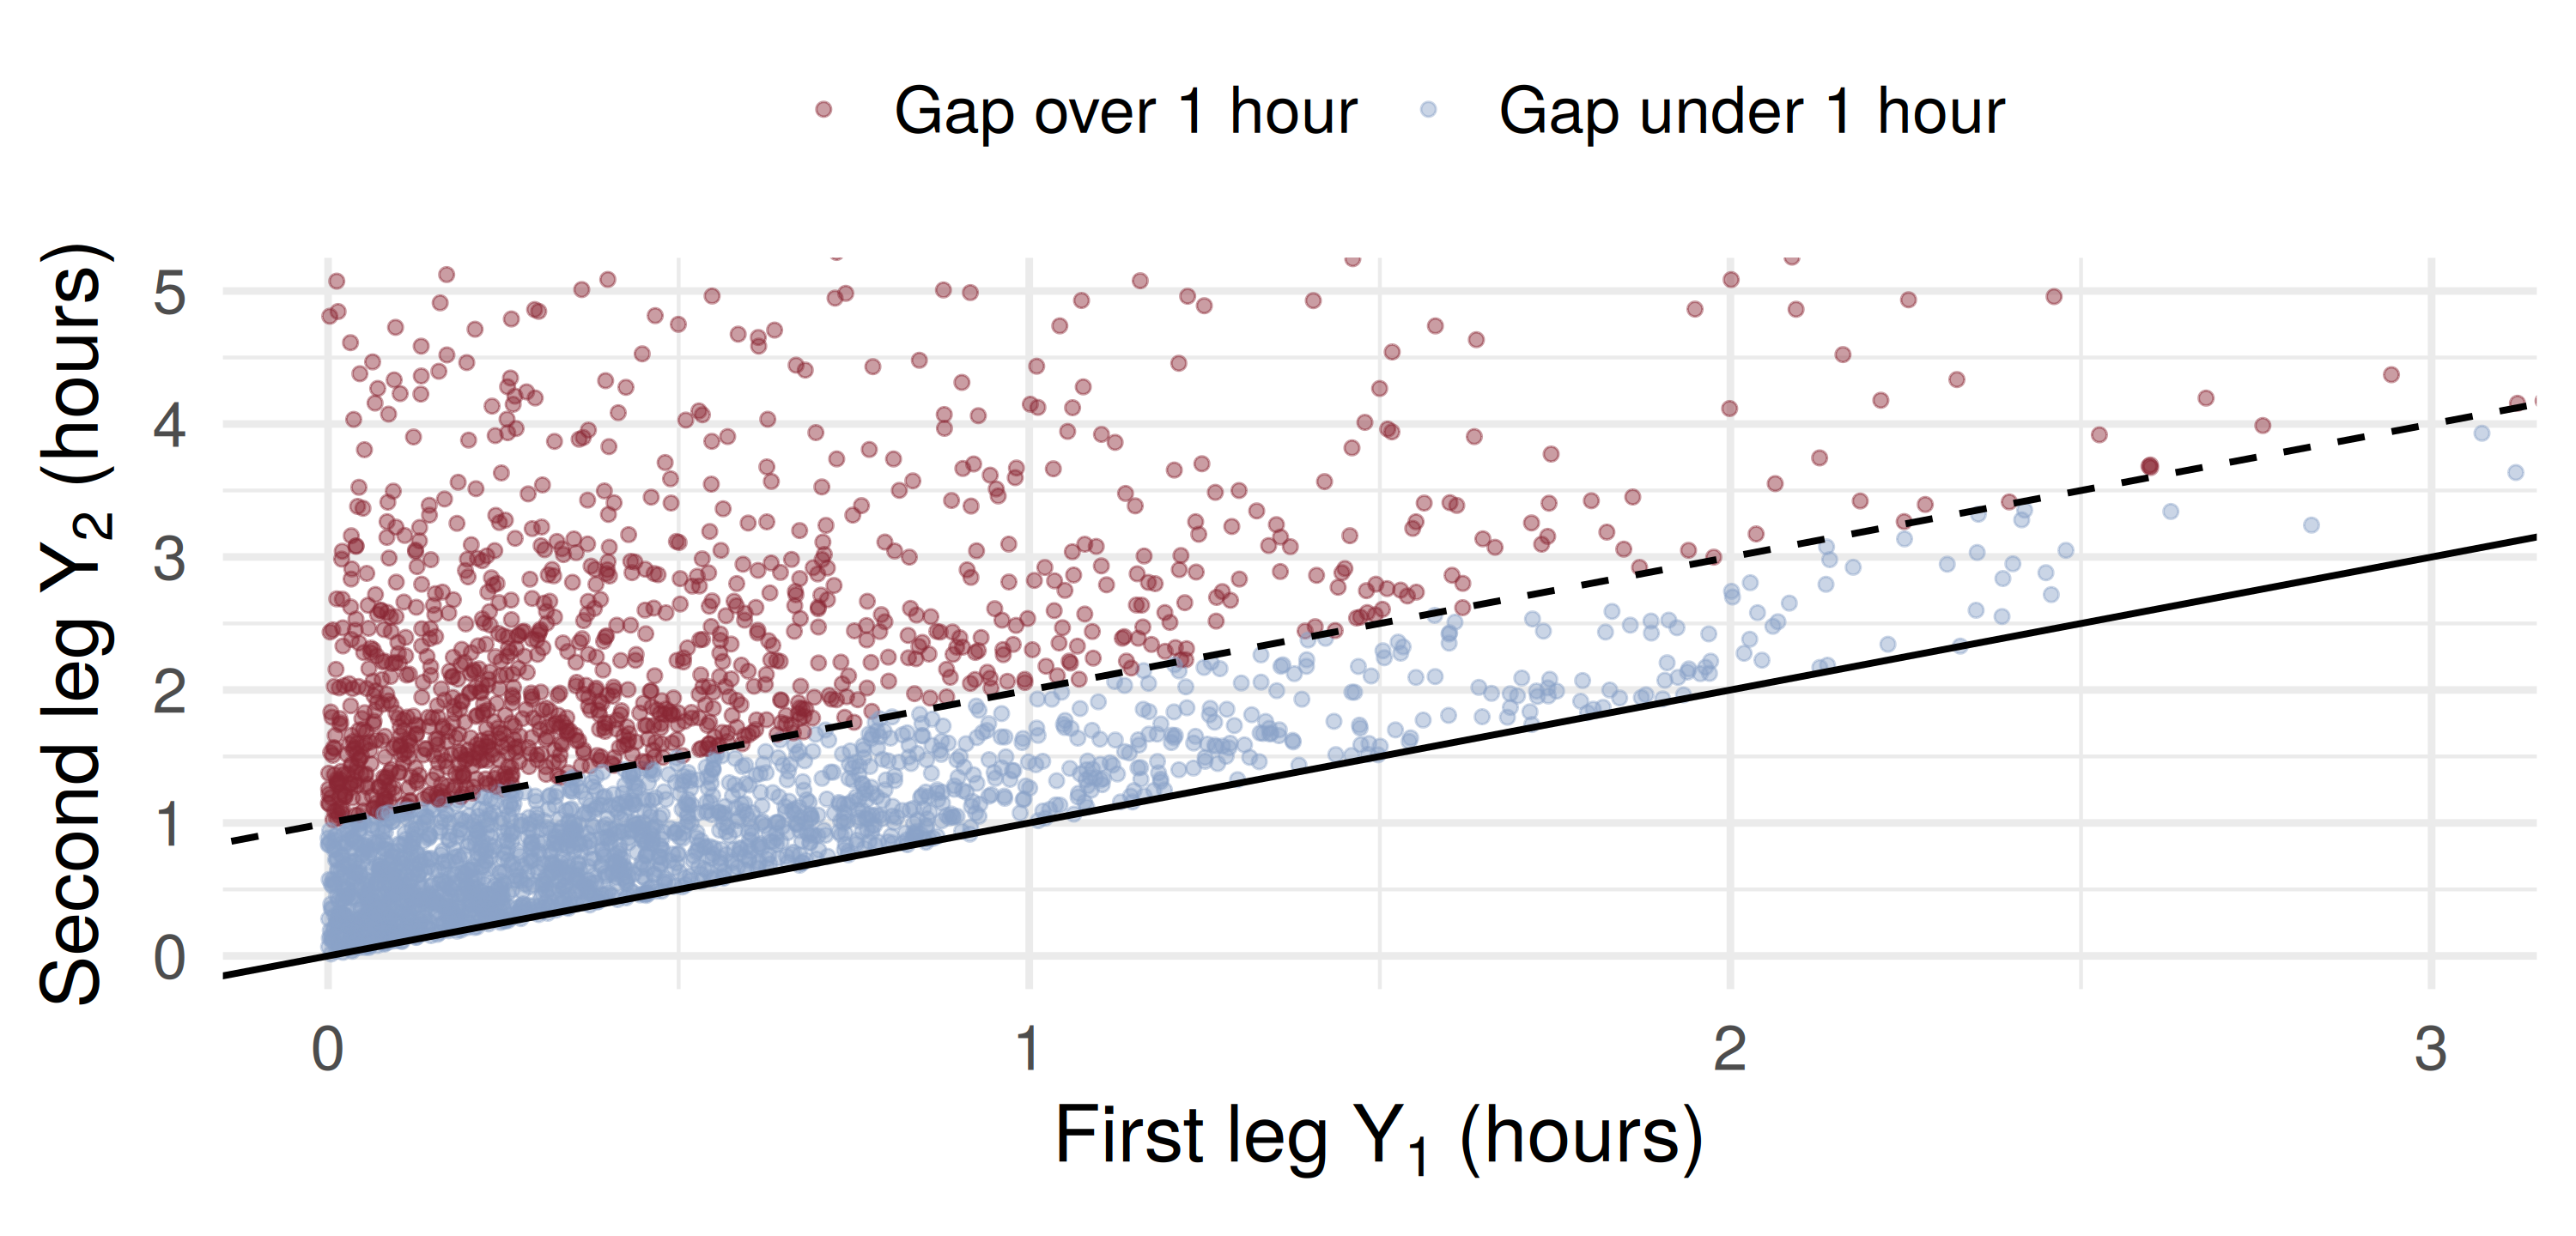
Sketch the region first. It is the part of the support above the line \(y_2 = y_1 + 1\). For each \(y_1\), \(y_2\) runs from \(y_1 + 1\) to \(\infty\): \[\int_0^{\infty} \int_{y_1 + 1}^{\infty} 2e^{-(y_1 + y_2)}\, dy_2\, dy_1 = \int_0^{\infty} 2e^{-1}e^{-2y_1}\, dy_1 = e^{-1} = 0.3679\]

More than a third of trades leave the bank exposed for over an hour.

💻 Checking the Integrals by Simulation

Code
# Two independent exponential(1) legs; the earlier is Y1, the later Y2.
# This pair has exactly the joint density 2exp(-(y1 + y2)) on 0 <= y1 <= y2.
n  <- 100000
a  <- rexp(n); b <- rexp(n)
Y1 <- pmin(a, b); Y2 <- pmax(a, b)
rbind(simulated = c(F_1_1 = mean(Y1 <= 1 & Y2 <= 1),
                    rect  = mean(Y1 <= 0.5 & Y2 > 1),
                    gap   = mean(Y2 - Y1 > 1)),
      exact     = c((1 - exp(-1))^2, 2 * exp(-1) * (1 - exp(-0.5)), exp(-1))) |>
  round(4)
           F_1_1   rect    gap
simulated 0.3981 0.2916 0.3689
exact     0.3996 0.2895 0.3679

A hundred thousand simulated trades land within \(0.003\) of all three integrals — the region and the limits were right.

🖼️ Where the Gap Lives

No point falls below the solid line \(y_2 = y_1\); the red points above the dashed line are the event.

🧠 Think-Pair-Share

Back to the two construction borrowers. \(Y_i = 1\) if borrower \(i\) defaults, \(0\) if not:

\(y_2 = 0\) \(y_2 = 1\)
\(y_1 = 0\) \(0.88\) \(0.05\)
\(y_1 = 1\) \(0.05\) \(c\)

Four minutes, in pairs: (1) find \(c\); (2) find the probability that at least one defaults; (3) compare \(P(\text{both})\) with \(0.07 \times 0.07\).

✅ Think-Pair-Share: Solution

  1. Theorem 5.1: the entries sum to 1, so \(c = 1 - 0.88 - 0.05 - 0.05 = 0.02\). Each borrower still defaults with probability \(0.05 + 0.02 = 0.07\).

  2. “At least one” fails only at \((0, 0)\): \(1 - p(0,0) = 1 - 0.88 = 0.12\).

  1. \(P(Y_1 = 1, Y_2 = 1) = 0.02\), about four times the \(0.0049\) that unrelated borrowers would give.

Same marginals, very different risk of a double loss. That is the opening question answered: only the joint table could say.

📝 Quiz #2: Making a Density Valid

A credit line’s limit \(Y_1\) and the amount drawn \(Y_2\) (million AZN) have constant density \(f(y_1, y_2) = k\) on the triangle \(0 \le y_2 \le y_1 \le 2\). What is \(k\)?

  • \(1/2\)
  • \(1\)
  • \(1/4\)
  • \(2\)

📋 Key Formulas

Statement
Definition 5.1 \(p(y_1, y_2) = P(Y_1 = y_1, Y_2 = y_2)\)
Theorem 5.1 \(p \ge 0\), \(\ \sum_{y_1, y_2} p(y_1, y_2) = 1\)
Definition 5.2 \(F(y_1, y_2) = P(Y_1 \le y_1, Y_2 \le y_2)\)
Theorem 5.2, part 3 \(P(y_1 < Y_1 \le y_1^*, y_2 < Y_2 \le y_2^*) = F(y_1^*, y_2^*) - F(y_1^*, y_2) - F(y_1, y_2^*) + F(y_1, y_2)\)
Theorem 5.3 \(f \ge 0\), \(\ \iint f(y_1, y_2)\, dy_1\, dy_2 = 1\)
\(n\) variables \(F(y_1, \ldots, y_n) = \int_{-\infty}^{y_1} \cdots \int_{-\infty}^{y_n} f(t_1, \ldots, t_n)\, dt_n \cdots dt_1\)

📋 Summary

  • Marginal probabilities alone cannot price a joint event; the joint distribution can

  • A joint probability function is a table of nonnegative entries summing to 1

  • \(F(y_1, y_2)\) accumulates mass below and to the left; differences of \(F\) give rectangles

  • For jointly continuous variables, probabilities are volumes under \(f(y_1, y_2)\)

  • Sketch the support and the event before writing the limits

  • Everything extends to \((Y_1, \ldots, Y_n)\) — the setting of every sample

📚 Practice Problems

Wackerly, 7th edition

  • Exercises at the end of §5.2 — start with 5.1, 5.3 and 5.4 (tables), then 5.5, 5.7, 5.9 and 5.11 (densities: sketch every region first)

  • On the settlement model, find \(P(Y_1 + Y_2 < 2)\) and check it with the simulation code above

Week 12, Problem Set 1 is open now and closes Sunday 6 December at 23:59 on WeBWorK, covering §5.1–5.2.

Next class: 28 November — marginal and conditional probability distributions (Wackerly §5.3): how to recover each borrower’s 7% from the joint table, and what one default says about the other.

🙏 Thank You

Dr. Samir Orujov
📧 sorujov@ada.edu.az
🏢 Building D, Room D325
🕓 Office hours: Wednesday, 16:00 – 18:00

Slides and readings: sorujov.net/teaching

❓ Questions

  • Given two marginal default probabilities of \(0.07\), what are the largest and smallest values \(P(\text{both default})\) can take?

  • Why must a joint density’s support be sketched before the limits are written, when a single density’s never had to be?

  • In the settlement model, is \(P(Y_2 - Y_1 > h)\) a shape worth knowing for every \(h\)? Guess its form from \(h = 1\).